Home Appraisals in Las Vegas: What Buyers and Sellers Should Know (2026)
A home appraisal is a licensed appraiser's opinion of what a home is worth, and if you're using a mortgage, your lender relies on it to decide how much it will lend. On the standard Las Vegas REALTORS® purchase agreement, a financed purchase can include an appraisal contingency: if the home appraises below the price, the buyer can renegotiate or cancel by the deadline and get their earnest money back (Residential Purchase Agreement, Rev. 10/25, Section 3B). Here's how it works for both sides.
Why the appraisal matters
- It can change the deal. A low value can mean renegotiating the price, adding cash or canceling.
- Buyers have a federal right to see it. Your lender must give you a copy of the appraisal promptly, or at least 3 business days before closing, whichever comes first (12 CFR 1002.14).
- You can challenge it. On loans sold to Fannie Mae, lenders must offer a borrower-initiated reconsideration of value process (Fannie Mae Selling Guide B4-1.3-12).
- Sellers can help the number. Good prep and a clear list of upgrades give the appraiser what they need.
I'm Andrew Guiant, a REALTOR® with Simply Vegas. I help buyers set appraisal deadlines that protect them, and I help sellers price so the appraisal supports the deal.
By Andrew Guiant, REALTOR®, Nevada License S.0183462, Simply Vegas · Updated October 27, 2026 · About a 7-minute read
Worried about an appraisal on a home you're buying or selling? Call or text me at 702-496-8216.
Who Does Appraisals in Nevada?
Appraisers in Nevada must hold a certificate, license or permit under NRS Chapter 645C, administered by the Nevada Real Estate Division. Acting as an appraiser without one is a misdemeanor (NRS 645C.260). The standard purchase agreement defines an appraisal as a written appraisal or notice of value required by a lender and prepared by a licensed or certified professional (RPA, Section 24).
The lender orders the appraisal, not your agent, and the contract's fee table says who pays for it. That cost is negotiable like the other fees (RPA, Section 9A).
How the Appraisal Contingency Works in Las Vegas
Section 3B of the standard contract works like this:
- The condition. Your obligation to buy is contingent on the home appraising for not less than the purchase price.
- The notice. If the lender or appraiser notifies you in writing that it appraised low, you can renegotiate or cancel.
- The deadline. You must deliver written notice to the seller, with a copy of the appraisal, no later than the number of calendar days after acceptance written in your contract.
- The refund. If you cancel in time, you're entitled to a whole refund of your earnest money.
- The waiver. If you don't cancel in writing by the appraisal deadline, the appraisal contingency is deemed waived.
Read how that deposit is protected in my earnest money guide. The appraisal deadline usually runs alongside your due diligence period and loan contingency, so I track all three together.
What Appraisers Look At
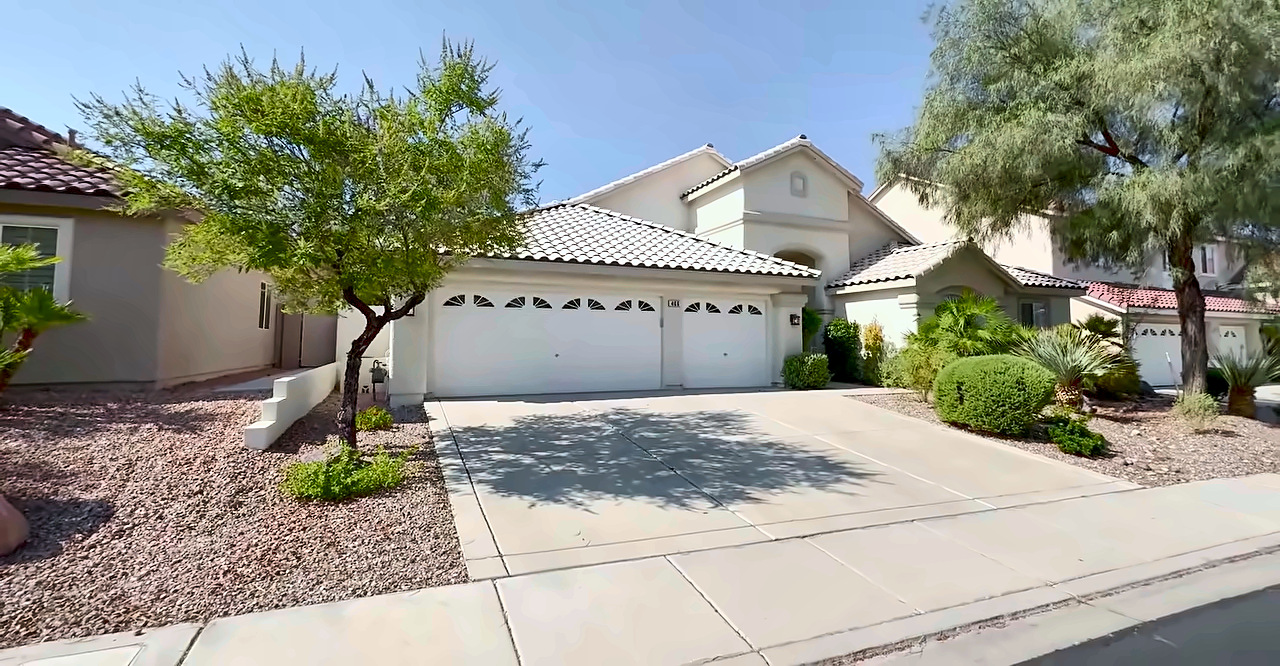
An appraiser compares the home with recent nearby sales and adjusts for the differences. For a Las Vegas home, that comparison usually comes down to:
- Size, layout and lot
- Condition and updates, such as a remodeled kitchen or new flooring
- Features buyers here pay for, like a pool, owned solar or RV parking
- The specific neighborhood or building, since a guard-gated community or a high-rise tower is its own small market
For context on prices, Las Vegas REALTORS® reported a median existing single-family home price of $470,000 in September 2026 (LVR). Your appraisal depends on your home's comparable sales, not the valley-wide median.
Your Right to a Copy of the Appraisal
Under federal law (12 CFR 1002.14), on a first-lien mortgage:
- Your lender must tell you in writing, within 3 business days of your application, that you have the right to a copy.
- They must give you a copy promptly when it's done, or 3 business days before closing, whichever is earlier. You can waive the timing and get it at closing instead.
- They can't charge you for the copy, though they can charge a reasonable fee for the appraisal itself.
What If the Appraisal Comes In Low?
You have a few options, and you need to act before your appraisal deadline:
- Renegotiate the price down to the appraised value, or meet in the middle.
- Cover the gap. You bring extra cash to make up the difference between the appraisal and the price.
- Ask for a seller credit or other concession to offset it, if your loan allows.
- Request a reconsideration of value (ROV). If you think the appraisal is wrong, see below.
- Cancel in writing by the deadline and get your earnest money back (RPA, Section 3B).
How a reconsideration of value works
For loans sold to Fannie Mae (Selling Guide B4-1.3-12; Fannie Mae ROV FAQs):
- The lender must give you a disclosure explaining its ROV process when it delivers the appraisal.
- You get one borrower-initiated ROV per appraisal.
- Your request has to identify what's unsupported, inaccurate or deficient, and you can submit up to five additional comparable sales with their sources, such as MLS numbers, plus an explanation.
- An ROV can be based on a value that's unsupported, deficient appraisal practices, or prohibited discriminatory practices.
- The lender, not the borrower, decides whether to accept the appraiser's conclusions.
I'll pull the comparable sales for an ROV with you. Other loan types have their own processes, so ask your lender how theirs works.
Do All Buyers Need an Appraisal?
- Cash buyers don't need a lender's appraisal, but you can still order one or write your own valuation terms into the offer.
- Some financed loans may qualify for what Fannie Mae now calls "value acceptance," its new name for what used to be called an appraisal waiver (Fannie Mae SEL-2025-07). Whether your loan qualifies is your lender's call.
Sellers: How to Prepare for the Appraisal
- Price it right from the start. A price your comparable sales support is the best protection against a low appraisal. My guide to getting the most money selling your Las Vegas home explains how I set it.
- Make a list of upgrades with dates, like a new roof, HVAC, water heater, pool equipment, solar or a remodel, so I can share it with the buyer's agent for the appraiser.
- Make every area accessible. That includes the attic, garage, pool equipment and any locked rooms.
- Present the home well. My prepare-to-sell checklist covers the repairs and cleanup that matter.
- Know the appraisal is just one step. See my full guide to selling a house in Las Vegas.
FAQ: Home Appraisals in Las Vegas
What happens if my Las Vegas home appraises low?
On the standard contract, the buyer can renegotiate or cancel in writing by the appraisal deadline and get their earnest money back. Other options include covering the gap, a seller concession or a reconsideration of value.
Can I get a copy of my appraisal?
Yes. On a first-lien mortgage, your lender must give you a copy promptly, or at least 3 business days before closing, at no charge for the copy (12 CFR 1002.14).
Can I dispute an appraisal?
On loans sold to Fannie Mae, you can request one reconsideration of value per appraisal, with up to five additional comparable sales.
Who pays for the appraisal in Nevada?
It's set in the purchase agreement's fee table and is negotiable (RPA, Section 9A).
Is an appraisal the same as an inspection?
No. An appraisal estimates value for the lender. An inspection checks the home's condition for you. See my due diligence guide.
Do condos and high-rises appraise differently?
Each tower is its own small market, so comparables usually come from the same building. See my high-rise condo guide.
Watch: Las Vegas Prices and the Market
 ▶ The $250 detail buyers notice · A small fix that changes first impressions |
 ▶ Quick market rundown · No-fluff Las Vegas market update |
 ▶ Prices down, rates up · Las Vegas real estate news |
 ▶ Market Watch: $1.5M home · What $1.5 million buys right now |
More videos: see them all on my YouTube channel.
Let's Make Sure the Numbers Work
Buying? I'll set an appraisal deadline that protects you and help you decide what to do if the value comes in low. Selling? I'll price your home on solid comparable sales and prepare the upgrade list the appraiser needs.
Looking now? Ask me about 222 Karen Ave #601 in Turnberry Towers and 1285 Raritan Pl, a 3-bedroom, 2-bath Henderson townhome built in 2019.
Andrew Guiant, REALTOR® | Simply Vegas
📞 702-496-8216
✉️ andrewguiant@gmail.com
🏠 Search homes: www.andrewsellsvegas.com
▶️ Home tours: YouTube @andrewsellsvegas
Ask Andrew about your home's value
This guide is general information, not legal or lending advice. Your signed contract and your lender's rules control. Information is deemed reliable but not guaranteed. Andrew Guiant, REALTOR®, Simply Vegas, NV license S.0183462.
Sources
- Las Vegas REALTORS® (GLVAR) Residential Purchase Agreement, Rev. 10/25 (Sections 3B, 8F, 9A, 24): https://lasvegasagentformula.com/wp-content/uploads/2026/07/10-2025-LVR-Residential-Purchase-Agreement-2.pdf
- 12 CFR 1002.14, rules on providing appraisals: https://www.ecfr.gov/current/title-12/chapter-X/part-1002/section-1002.14
- Fannie Mae Selling Guide B4-1.3-12, Appraisal Quality Matters: https://selling-guide.fanniemae.com/sel/b4-1.3-12/appraisal-quality-matters
- Fannie Mae, Reconsideration of Value FAQs (Sept. 3, 2025): https://singlefamily.fanniemae.com/initiative-updates/reconsideration-value-rov
- Fannie Mae, Announcement SEL-2025-07: https://singlefamily.fanniemae.com/news-events/announcement-sel-2025-07-selling-guide-updates
- NRS Chapter 645C (appraisers): https://www.leg.state.nv.us/nrs/NRS-645C.html
- Las Vegas REALTORS®, September 2026 statistics: https://members.lasvegasrealtor.com/statistics/pdf/2026-09-GLVAR-Article.pdf
- Andrew Guiant, Green Valley home tour: https://www.youtube.com/watch?v=Jxz397BdMVQ
- All checked October 27, 2026.
Categories
- All Blogs (39)
- Aries (1)
- Buyer Tips (29)
- Communities (1)
- Community Guides (11)
- Golf Communities (4)
- Henderson (11)
- Henderson Events (1)
- High-Rise Condos (7)
- Las Vegas Communities (23)
- Las Vegas Events (1)
- Living in Las Vegas (6)
- Model Home Tours (1)
- Moving to Las Vegas (2)
- New Construction (5)
- Relocation (5)
- Seller Tips (13)
- Southwest Las Vegas (1)
- Things to Do (2)
Recent Posts


GET MORE INFORMATION